What Singapore’s New Stablecoin Rules Mean for Trading


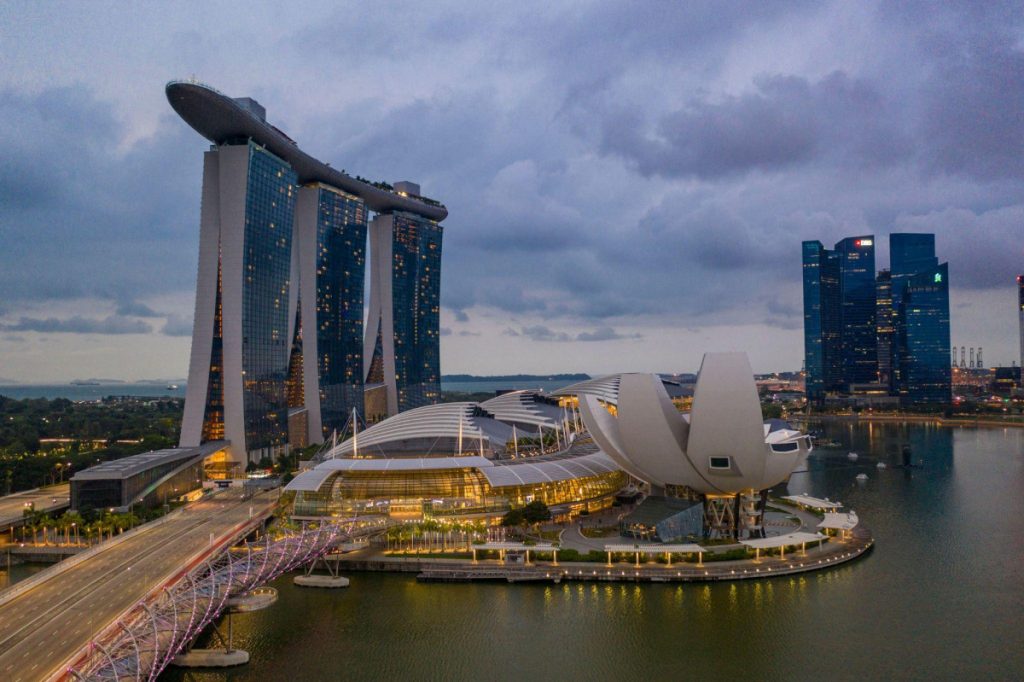
Singapore has spent years building a digital asset market that supports useful financial technology without treating every crypto product in the same way. Its approach to stablecoins is another step in that direction.
Rather than giving the wider crypto market a regulatory green light, the framework draws clearer boundaries around which stablecoins can meet defined standards. That matters because these tokens increasingly sit between conventional finance and digital markets, particularly when they’re used to transfer value or support settlement.
For traders, the changes also make it more important to understand the difference between the asset being used, the product being traded and the company providing access to financial markets.
What Stablecoin Framework Actually Changes
Stablecoins are designed to maintain a relatively consistent value by being linked to another asset, commonly a fiat currency. Yet the word “stable” alone says little about the quality of the token behind it.

That’s where regulation makes a difference. Singapore’s framework establishes requirements around areas such as reserve assets, redemption and disclosure for stablecoins that fall within its scope. Users therefore have a clearer basis for understanding what stands behind an eligible token rather than relying entirely on an issuer’s promises.
For the wider digital asset sector, that’s a big difference. Stablecoins are increasingly being discussed as financial infrastructure rather than simply another asset to speculate on. They can provide a bridge between traditional currencies and blockchain-based markets, which is also relevant to people involved in forex trading as the boundaries between conventional and digital financial markets continue to develop.
Confidence in how these tokens are backed and redeemed becomes particularly important.
However, clearer standards don’t mean every stablecoin or crypto product suddenly falls into the same regulatory category.
Stablecoins and Crypto Trading Aren’t the Same Thing
This is perhaps the most important distinction for traders.
A stablecoin that meets a particular regulatory standard is different from buying cryptocurrency on a spot exchange. Both are different again from taking a position on the price of a digital asset through a contract for difference, or CFD.
Those differences determine what users actually own and which regulatory requirements apply.
Someone holding a token directly may need to consider custody and the security of the wallet or exchange holding the asset. With a CFD, the trader doesn’t own the underlying cryptocurrency. Instead, the contract follows movements in its price.
Singapore’s developing regulatory structure doesn’t remove distinctions within digital assets, but it makes them harder to ignore.
Where Regulated Brokers Fit Into the Picture
The changing environment also puts more attention on the companies providing access to financial markets.
OANDA Asia Pacific holds a Capital Markets Services Licence issued by the Monetary Authority of Singapore. Residents can apply for an account with the locally regulated entity, although applications remain subject to regulatory requirements and individual assessment.
This becomes relevant when digital assets are viewed alongside established markets. As crypto-linked products and stablecoins move closer to traditional financial markets, understanding the regulatory status of both the product and its provider becomes increasingly important.
But regulation of a broker shouldn’t be confused with regulation of every underlying asset associated with its products.
The company’s Singapore offering includes cryptocurrency CFDs, meaning traders speculate on price movements rather than buying and storing the underlying digital tokens. CFDs are leveraged products and carry substantial risk, so the regulatory status of the provider doesn’t remove the risks associated with the market itself.
The more useful distinction is that the broker operates within regulatory framework for the activities covered by its licence. That helps traders understand the company they’re dealing with while still requiring them to understand the particular product they choose to trade.
Regulation Could Change How Traders Judge Platforms
For years, crypto platforms were often compared based on the number of tokens they offered, their fees or how quickly users could begin trading.
Singapore’s approach introduces another consideration: exactly what regulatory framework sits behind the service.
This becomes especially relevant as digital assets overlap more closely with established financial markets. Stablecoins can potentially be used for payments and settlement, while crypto prices can also be accessed through instruments such as CFDs. These activities may appear connected from a user’s perspective, but they don’t necessarily carry the same legal treatment or protections.
A platform’s regulatory status tells traders something important about the company providing the service, but it shouldn’t be mistaken for a guarantee about the underlying asset.
For OANDA, its MAS licence provides a clear regulatory position. What traders still need to establish is what they’re actually trading and how that particular product works.
Stablecoins Could Become More Useful as Financial Infrastructure
The longer-term effect of Singapore’s rules may have less to do with encouraging speculative activity and more to do with making certain stablecoins more credible for practical financial use.
Reliable redemption and reserve requirements come into play when a token is being used to move value between different parts of the financial system. Businesses and financial institutions need to understand what backs an asset and how it can be converted back into conventional currency.
That doesn’t remove market or operational risk. What it can do is establish clearer expectations for issuers that want their stablecoins recognised within Singapore’s framework.
This also explains why the country’s approach shouldn’t be read as a broad endorsement of cryptocurrency. Regulators can see potential value in blockchain-based settlement while continuing to take a cautious approach towards speculative digital asset activity.
The two positions aren’t contradictory. A token being used as financial infrastructure serves a different purpose from an asset bought primarily because someone expects its price to rise.
A More Clearly Divided Digital Asset Market
Singapore’s framework points towards a digital asset sector in which the lines between different products become more visible rather than disappearing.
Stablecoins that meet defined requirements can occupy one part of that market, while spot cryptocurrencies, token custody and leveraged instruments remain separate activities with their own considerations.
Traders need to consider regulation at more than one level. There is the status of the asset itself, the type of product being traded and the regulatory position of the company providing access to it.
OANDA illustrates that distinction well. Its Asia Pacific entity operates under a MAS Capital Markets Services Licence, while crypto CFDs remain leveraged products that carry substantial risk. Regulation of the provider should therefore never be interpreted as removing the risks associated with the underlying market.
As Singapore continues developing its digital asset rules, understanding the difference between the token, the trading product and the provider could become increasingly important for anyone navigating the market.
Disclaimer
In line with the Trust Project guidelines, please note that the information provided on this page is not intended to be and should not be interpreted as legal, tax, investment, financial, or any other form of advice. It is important to only invest what you can afford to lose and to seek independent financial advice if you have any doubts. For further information, we suggest referring to the terms and conditions as well as the help and support pages provided by the issuer or advertiser. MetaversePost is committed to accurate, unbiased reporting, but market conditions are subject to change without notice.
About The Author
Gregory, a digital nomad hailing from Poland, is not only a financial analyst but also a valuable contributor to various online magazines. With a wealth of experience in the financial industry, his insights and expertise have earned him recognition in numerous publications. Utilising his spare time effectively, Gregory is currently dedicated to writing a book about cryptocurrency and blockchain.
More articles
Gregory, a digital nomad hailing from Poland, is not only a financial analyst but also a valuable contributor to various online magazines. With a wealth of experience in the financial industry, his insights and expertise have earned him recognition in numerous publications. Utilising his spare time effectively, Gregory is currently dedicated to writing a book about cryptocurrency and blockchain.